Term Insurance Plans in UAE, Dubai
A term insurance plan is one of the simplest and most affordable ways to secure your family's financial future. It offers high life cover at relatively low premiums and can be enhanced with additional benefits such as critical illness cover, accidental death benefit, and waiver of premium riders. It helps you manage living expenses, outstanding loans, children's education, and other financial responsibilities.read more
4.7/5
46,418
 Reviews
Central Bank UAE Registration No.: - 123
Insurance Partners
Trusted Customers
Policies Sold
 PB PromiseBest
Price Guarantee
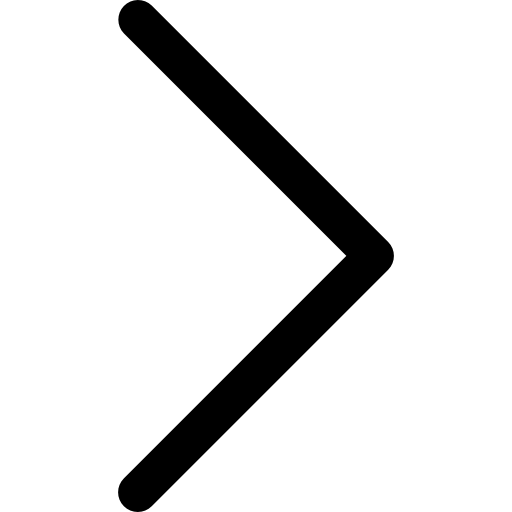
Starting @ AED 50/month*


 Qualified Policybazaar expert will assist you
 Aashima Mongia


What is Term Insurance?
A term insurance plan is a financial security plan that offers a safety cushion to the life assured’s family in case the former passes away during the policy period. It is a pure life cover that usually offers only a death benefit.
Why Is Term Insurance Important in the UAE?
Unlike in many home countries, UAE expats have no government pension, state benefits, or automatic death-in-service gratuity beyond 21 days per year. If you pass away during your employment, your family's visa is cancelled within 30 days, with no income replacement. Term insurance is the only product that fills this gap instantly- Term insurance is a fixed-period life insurance plan that protects your family financially if something happens to you during the policy term.
- Compare plans from leading insurers with premiums starting from just AED 50*/month and life cover of up to AED 1 million.
- Choose from flexible term plans with coverage periods ranging from 5 to 35 years, along with optional benefits such as critical illness and accidental death cover.
- All plans available through Policybazaar.ae are offered by insurers regulated by the Central Bank of the UAE and follow UAE insurance regulations and guidelines.
Term Insurance UAE at a Glance (Quick Specifications)
| Particulars | Specification |
|---|---|
| Term Insurance Cost | Starting at AED 50 |
| Plan Coverage Amount | AED 1 million |
| Minimum Entry Age | 18 years |
| Maximum Entry Age | 65-79 years depending on the insurer |
| Term Insurance Plans Tenures |
Starting 5 years to 35 years |
| Countries Covered | 190+ Countries covered |
| Coverage |
|
| Who Should Buy a Term Insurance |
|
| Features & Benefits |
|
| Claim procedure | Can Claim both online and offline |
| Claim Settlement Ratio | 94-98% |
The mentioned details are based on Policybazaar.ae data, updated as of September 2026, based on a sample customer profile. Your premium may be lower or higher.
Term Life Insurance for Expats in the UAE
Expats can buy term insurance in the UAE. Most CBUAE-licensed insurers offer plans for UAE residents, and the application process is generally similar for expats and UAE nationals.
Who can buy term insurance?
Anyone with a valid UAE residency visa and Emirates ID can apply for term insurance from a CBUAE-licensed insurer.
Most plans start at age 18. The maximum age for new applications can range from 65 to 70 years, depending on the insurer and plan. There is no nationality restriction.
What do insurers check?
Four main factors usually affect your approval and premium:
- Age: Younger applicants generally pay less. For example, a 30-year-old non-smoker can get AED 1 million cover for AED 58 a month. At age 45, the same cover could cost around AED 325 or more per month.
- Health: A pre-existing condition doesn't always mean your application will be rejected. The insurer may charge an extra premium or exclude the condition.
- Smoking: Smokers generally pay more than non-smokers. The difference can be 40% to 60% for the same age and cover amount.
- Occupation: Office and professional jobs are usually considered standard risk. Jobs such as construction, piloting, offshore oil work and other high-risk roles may need additional underwriting or cost more.
Which documents do expats need to get term insurance?
For a digital application, you will usually need:
- Emirates ID
- Passport
- UAE residency visa
Depending on the cover amount, you may also need proof of income, such as a salary slip or bank statement.
For high-risk jobs, the insurer may ask for an employer letter or details about your work. For larger cover amounts, usually above AED 2 million, the insurer may also require a medical examination. The insurer generally arranges this, with no test-related cost for the applicant.
Does term insurance provide worldwide coverage?
Most term insurance plans in the UAE cover death worldwide. So, if you die outside the UAE during the policy term, your beneficiary can receive the sum assured, subject to the policy terms.
You can also usually continue paying premiums and make a claim while living abroad. Before moving, check whether your policy allows overseas premium payments and claims.
Regulation and Trust: The Role of the Central Bank
Policybazaar.ae is regulated by the Central Bank of the UAE (CBUAE) with Registration No.: 123 and Emirates Insurance Federation Registration number B81. The CBUAE Rulebook serves as the primary resource for regulations and standards mentioned in our article.
The CBUAE Framework
All term insurance policies distributed in the UAE are strictly underwritten by insurance companies licensed and regulated by the Central Bank of the UAE (CBUAE). This central regulatory oversight ensures that insurance companies maintain mandatory capital solvency margins to honour long-term claims, providing legal protection for your policy.
The Mandatory Free-Look Period
Under consumer protection rules mandated by the CBUAE, every term life insurance policy issued in the UAE includes a free-look period of 15 to 30 days from the date of physical or electronic policy delivery.
During this window, you have the legal right to review the fine print. If you find hidden exclusions or are unsatisfied with the policy terms, you can cancel the plan and receive a 100% refund of your premium, free of cancellation fees or exit loads.
 Directly from experts
15+ years in UAE life insurance & wealth management
Best Term Insurance Plans in UAE
Here are the best term insurance quotes in UAE:
Types of Term Life Insurance in UAE – Which One Should You Buy?
There are various types of term plans in UAE that you can choose as per your security needs and family obligations:
Level Term Insurance
Increasing Term Plan
Decreasing Term Plan
Convertible Term Insurance
How Term Insurance Works for UAE Expats: Step-by-Step


Example for UAE Residents


Features of a Term Life Insurance Plan


Young Professionals
Parents
Recently Married Couples
Self-Employed Applicants
Single Mothers and Working Women
If you recently entered your professional life, it is the right time to buy term insurance in UAE. Why? Because it is cheaper when you are young and below 30 years of age. It also sets you in the right habit of managing your money. It also gives you coverage at a young age, which can be useful if you take out a loan, a car, or a house later.
Kids need a lot: school, clothes, food, and a house. If you're a parent, your family depends on your income. Term life insurance protects your children and your spouse so they still have funds and income even when you're not around.
Marriage comes with its costs and responsibilities. You can start saving to buy your new car, a house where you can live, or even start planning children. By adding term insurance in Dubai, you can ensure that your spouse is not left with enormous payments alone if unfortunate circumstances arise.
If you have a business of your own, you have variable income. You also don't have insurance through your employer. Term life insurance is a safety net. At worst, your family still has funds to survive.
Nowadays, many women are sole breadwinners for their households. If you have kids and there is no other earning member in your household, your salary is even more important. Term life insurance ensures that your kids will be okay, regardless of what happens.
Common Mistakes People Make When Buying Term Insurance in UAE
1. Buying Late
Many people delay buying term insurance, thinking they can do it ‘someday’. But the longer you wait, the higher your premium gets. In fact, you may even lose eligibility for a high life cover if health issues develop.
2. Choosing a Low Life Cover
Ideally, your life cover should be at least 15–20 times your annual income. This way, your family can manage expenses, loans, and long-term goals without financial stress.
3. Ignoring Riders
For a small extra premium, riders like critical illness, waiver of premium, or accidental death benefit can offer financial support when unexpected events occur.
4. Hiding or Withholding Information
Some people skip sharing medical or lifestyle details to get lower premiums, but this can backfire. If the insurer discovers missing information during claim verification, the claim can be denied.
Example: If a smoker hides their smoking habit, the insurer can easily trace it through medical records during a claim investigation and may reject the claim entirely.
How to Find the Right Term Insurance Plan in UAE?
Here’s how you can find the best term life insurance policy for yourself -
- Compare plans from multiple insurance providers
- Check the Claim Settlement Ratio (CSR) of insurers - this figure gives the idea of the number of claims settled against the total claims received
- Understand your requirements - when getting term insurance Dubai, consider your current income and liabilities as well as your family’s needs, future plans, and more
- See how easy the claim settlement process is - go with a company that has a straightforward process so that you don’t have to rush in time of emergency
- Look for a plan that offers riders or add-ons - you can use them to increase the coverage of your term insurance UAE at nominal additional prices
How to Buy Term Insurance Online from Policybazaar.ae?
With Policybazaar.ae, getting the best term policy is just a matter of a few clicks. Here’s how we help you get the best term insurance in UAE in 5 simple steps:

When you buy term life insurance online via Policybazaar.ae, you get an additional advantage of expert assistance to help you wherever you get stuck. Alternatively, you can visit your selected provider’s nearby office and submit your application in person.
Best Term Insurance Companies in 2026 by Claim Settlement Ratio
| Insurer Name | Plan Name | Claim Settlement Ratio | Min Age | Max Age | Min Premium |
|---|---|---|---|---|---|
| Takaful Emarat | Fixed Term | 98.20 % | 20 | 60 | 71 AED/Monthly |
| MetLife | Live Life Now | 98.00 % | 21 | 60 | 20 AED/Monthly |
| MetLife | Live Life | 98.00 % | 21 | 60 | 350 AED/Monthly |
| Zurich Insurance | International Term Assurance | 97.00 % | 18 | 74 | 385 AED/Monthly |
| Arabia Insurance | Critical Illness Basic | 95.00 % | 18 | 60 | 4 AED/Monthly |
| Arabia Insurance | Term Life | 95.00 % | 15 | 70 | 50 AED/Monthly |
Documents Required to Purchase Term Life Insurance
How to Decide the Right Tenure for a Term Insurance Policy?
Is term insurance refundable?
Your premium is refunded only if you cancel your policy during the free-look period or if you opt for the return of the premium rider. Term policy premium is non-refundable otherwise.
How to calculate term insurance?
Term cover can be easily calculated by using an online term insurance calculator. Here, you need to input a few details like the desired coverage amount, desired policy term, age, gender, health, lifestyle habits, and more.
Can I withdraw money from my term life insurance in Dubai?
Withdrawal of money from term life insurance is generally not allowed as it is designed to provide a death benefit to beneficiaries upon the insured's death. However, some policies may offer options like policy loans or partial surrenders under certain conditions.
How to sell term life insurance?
Selling your term life insurance may not reap you a big amount. It is rather beneficial to convert it into a life insurance policy, if your resources & the policy allows. However, if you still wish to sell your policy, you can do so by finding a reputed broker who will charge a fee for selling it.
Can expatriates buy term insurance in the UAE?
Yes. Expats with a valid Emirates ID and UAE residency visa can buy international or local term policies. These plans generally feature worldwide portability, meaning your cover remains fully active if you relocate back home or move to a new international destination.
How does UAE inheritance law affect beneficiary designations?
For non-Muslim expatriates, it is highly recommended to register an official asset-preservation will through the DIFC Wills Service Centre. This ensures that your named beneficiary designations bypass default local statutory inheritance rules and are executed smoothly according to your wishes.
Can I change my named nominee after buying a policy?
Yes. You can update, add, or alter your designated beneficiaries at any point during your policy's active lifespan. For this, you just need to submit a basic endorsement form to your insurance provider.
Is there a grace period for missed premium payments in the UAE?
Yes. Most UAE-licensed insurance carriers provide a mandatory 30-day to 60-day grace period for missed monthly or annual premium payments before a policy officially lapses, protecting you against accidental coverage loss.
Can I buy term insurance without medical tests?
Yes, some insurers in the UAE offer term insurance without medical tests through simplified underwriting. Instead of undergoing physical examinations, eligible applicants may only need to complete a health declaration, lifestyle questionnaire, and identity verification.
What happens to my term life insurance if I leave the UAE?
In many cases, your term insurance policy can continue even if you move out of the UAE, provided you keep paying premiums on time and your policy includes worldwide portability.
Does term insurance cover critical illness?
Standard term insurance typically covers death during the policy period and does not automatically include critical illness benefits. However, many insurers allow you to add a critical illness rider for an additional premium.
What if I'm denied term insurance in the UAE?
If an insurer declines your application because of your age, health, medical history, occupation or other underwriting factors, remember different insurers have different underwriting guidelines. So, try another insurer, consider a lower coverage amount, or explore employer-provided group life insurance. Always disclose your medical history accurately when applying, as providing incorrect or incomplete information can affect your coverage and claims. Policybazaar.ae agents can advise you on other insurers that may be more flexible with their underwriting requirements for your situation.
Can I keep my term insurance in the UAE if I go back to my home country?
Yes, you can keep your term life insurance policy in the UAE if you return to your home country; however, make sure you have worldwide cover. Before you leave, ensure your policy allows you to pay for your insurance abroad. You should also let your insurer know that you are changing residences.
Can I make a claim on my term life insurance if I pass away outside the UAE?
Most policies will allow you to make a claim if you pass away outside the UAE. Your family may need to provide an overseas death certificate, medical documents and anything else requested by your insurer. Please ensure your policy has no geographical exclusions, and let your insurer know if you are relocating.
Will my policy pay out if I die of natural causes within the first year?
In most cases, yes. Most term life insurance policies will cover natural causes. As long as you pay your premiums and provide your medical history truthfully, your policy should cover you. There may, however, be exclusions for certain situations, such as suicide during the exclusion period.
Can I use my employer’s Death in Service insurance?
No, it is not advised to only rely on your employer’s insurance. This is usually group insurance and will be tied to your employment. Personal term life insurance can provide extra protection and may be independent of your job.
Can I keep my personal term insurance if I change my visa type to a Golden Visa?
You should still be able to keep your personal term insurance. Let your insurer know you are changing your visa to avoid any issues with your insurance. Your insurance is unrelated to your residency. However, your insurer may want to see some updated documents.
Do I need a DIFC Will if I have a nominated beneficiary?
No, you don’t necessarily need one. However, having a nominated beneficiary will not cover your whole estate. A DIFC Will may allow eligible non-Muslims to decide how they want to distribute their UAE assets. It may also let you nominate guardians for any eligible minors. Speak to a legal professional to understand what best suits your situation.
Is there a grace period if I forget to pay my premium?
Many term life insurance policies will allow you a grace period. This is usually around 30 days. Please pay your premiums as soon as possible. Your cover may still be valid whilst within your grace period. Please check your policy documents.
Can my insurer increase my premium?
If you have a guaranteed premium for the agreed term, then your insurer will not usually increase it. If you have a policy that allows for review, or you wish to change your cover, then your premiums may be altered. Please check your schedule to see if you have a guaranteed premium.
Will my premium reduce if I stop smoking?
Your premium will not usually reduce automatically. Please contact your insurer to see whether they offer a review. You may need to meet their non-smoker criteria, and they may require further underwriting.
Can I take out more than 1 term insurance policy in the UAE?
Yes, you can usually take out multiple term life insurance policies. As long as the claim falls within your policy terms, both policies may pay out. When applying, declare any cover you already have. Your insurer may consider your total cover and your financial needs.
Is a term life insurance payout taxed in the UAE?
The UAE does not have a personal income tax so your payout should not be taxed. However, your home country or any tax residency countries may have different rules. If you are making a claim into another jurisdiction, then please seek tax advice.
What should my family do if I die whilst living in Dubai?
Your family or nominated beneficiary should contact your insurer. They should find your policy documents, prepare a death certificate, claim form, your beneficiary's details, and any required medical or police reports. Your insurer will tell you how to submit your claim. They may ask for additional documents. This may be the case if you passed away abroad or under unusual circumstances.






More From Term Insurance
- Recent Articles
- Popular Articles
 Last Updated : 04 Nov 2026Term Insurance Benefits in UAE: 8 Key AdvantagesExplore 8 term insurance benefits in the UAE: high cover at low premiums, loan protection, riders and worldwide cover. Compare plans on Policybazaar.ae.
 Last Updated : 04 Nov 2026Is Life Insurance Payout Taxable?Life insurance payouts aren't taxed in the UAE, but Indian policies follow Indian tax law. See NRI rules for death, maturity and ULIP payouts, TDS and DTAA.
 Last Updated : 04 Nov 20268 Benefits of Life Insurance in UAE for Residents & ExpatsDiscover 8 benefits of life insurance in the UAE, from income replacement and loan protection to children’s education and riders. With AED examples.
 Last Updated : 11 Nov 2026Smart Return Term Plan UAE: Premium Refund & TROP ComparisonAlliance’s Smart Return Term Plan refunds base premiums via the Smart Exit Benefit on 30-year policies. See eligibility, exclusions and how it compares with TROP.
 Last Updated : 15 Oct 2026Term Insurance Maturity: Benefit, Value & What Happens (UAE)Does term insurance have maturity benefit? See the meaning, why pure term plans pay no maturity value, return-of-premium options, and what to do when cover ends.
- Last Updated : 15 Oct 2026Life Insurance Maturity Benefit: Meaning, Value & Payout UAELife insurance maturity explained for UAE policyholders: maturity date vs benefit, maturity value vs surrender value, the maturity period, tax and the claim process.
 Last Updated : 17 Sep 2026Top Life Insurance Companies in Dubai, UAE 2026 | Compare Top ProvidersCompare top 10 life insurance companies in UAE , Zurich (98% CSR), MetLife, HAYAH & more. CBUAE-licensed. Get instant quotes. Explore top providers and choose a plan that fits your needs.
 Last Updated : 26 Aug 2026Term Insurance for Self-Employed in UAE 2026 | From AED 50*/MonCompare the best term insurance plans for self-employed individuals in UAE. No employer cover? Secure AED 1M life cover from AED 50/month. Get free quotes now.
 Last Updated : 02 Oct 2026Term Insurance for NRI | Best Term Insurance Plan for NRI in UAETerm Insurance for NRI - Compare and Buy best term insurance policies for NRI in UAE & know important things before buying the term plan for NRI in UAE.
 Last Updated : 23 Mar 2026Term Insurance for Spouse in UAE - Features & BenefitsTerm Insurance for Spouse - Choose the best term insurance plan for your spouse in UAE with features & Benefits. Also, know who can buy a spouse term insurance plan.
 Last Updated : 12 Dec 2025Top Life Insurance Plans for Expats in the UAE: Protect Your Family's FutureDiscover the best life insurance options for expatriates in the UAE. Learn about key benefits, top plans, and essential tips to secure financial protection for your loved ones.
 Last Updated : 19 Sep 2025Short Term Disability Insurance | Benefits & How It WorksDiscover short term disability insurance options to safeguard your income during challenging times. Get affordable coverage tailored to your needs!


 Reviews